
The REAL Reason Trump is Invading Iran (From Banyan Hill Publishing)
Key Points
- High institutional ownership signals that ADM, Sanmina, and Delek US Holdings, though overlooked, may be worth buying.
- ADM's scale advantage across roughly 750 facilities and its 53-year dividend growth streak underpin its cash flow strength despite a low-margin business.
- Sanmina's AI manufacturing partnerships and Delek's widening crack spreads are catalysts that analysts appear to be underestimating heading into 2027.
- Special Report: [Free Report] The 11-Hour Options Guide for Beginners - trade and ticker included (From Base Camp Trading)
Overlooked stocks worth buying aren’t easy to find, as, usually, when the market ignores a stock, it's for a good reason. However, a sure sign that an unloved or under-reported name is a winner is high institutional ownership. Institutions are unlikely to invest in a risky, cash-burning name without a reason, so following their lead is often profitable.
Other qualities that strengthen the bull case for an overlooked stock are value, cash flow, and yield, which are the only things that really matter—even high-profile tech stocks move on cash flow and yield; it is the aggressive, often explosive growth, wild forecasts, and emotional markets that make their stock prices move so much.
The energy story near the Grand Canyon (Ad)
The largest energy source on Earth contains 50,000 times every oil and gas reserve on the planet combined - and much of it sits beneath the desert near the Grand Canyon.
A drilling crew just hit the DOE's 2035 targets twelve years early, with costs down 50% in 18 months. Google signed on, Gates invested, and the Pentagon made it a priority. One company has been quietly building this infrastructure for sixty years.
See the company sitting on the biggest energy source on Earth
Archer-Daniels-Midland: A Cheap Dividend With a Giant Moat
Archer-Daniels-Midland (NYSE: ADM) is an often-overlooked company because of its non-flashy, low-margin, commodity-driven business. Investors often overlook the company’s moat and countercyclicality, which enable wider margins and lower working capital during commodity downturns.
The strength is tied to the business model, which relies on commodities but not necessarily on higher commodity prices. ADM grinds and crushes nuts and seeds, converts beets and sweet potatoes into sugar, and provides many other services, making money on the spread.
The moat comes from scale: ADM’s global network includes approximately 750 collection and processing facilities, giving it a vast infrastructure footprint that would be extremely difficult for a competitor to replicate.
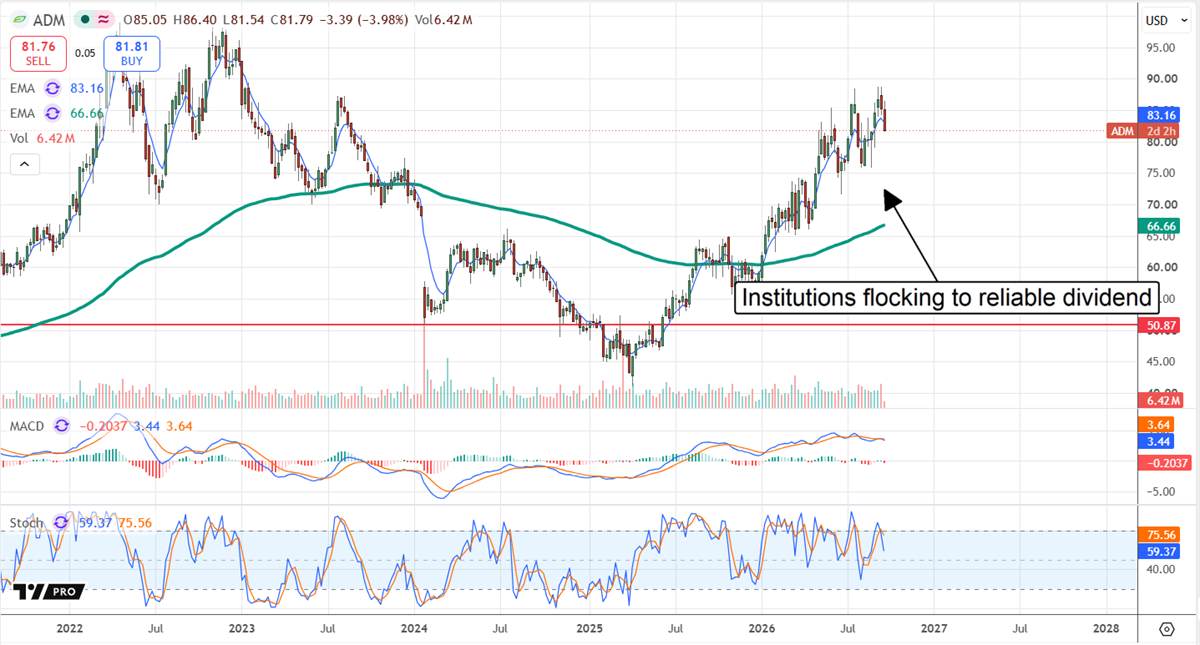
ADM is a good buy because of its cash flow, dynamic capital allocation model, and ability to sustain annual dividend increases. The company is laser-focused on its dividend-growth trajectory, which includes 53 consecutive years of annual increases. Share buybacks are also in the picture, coming at opportunistic times when cash flow allows. Eight analysts rate ADM as a consensus Hold, while institutions own nearly 80% of the stock and are aggressively accumulating.
Sanmina: The Muscle in Tech Manufacturing
Sanmina (NASDAQ: SANM) is an often overlooked stock because it works behind the scenes, providing outsourced manufacturing solutions to the tech industry. The low-profile business lacks product recognition, even though it makes devices for names such as Advanced Micro Devices (NASDAQ: AMD). Additionally, its mid-cap size and low growth keep it out of the spotlight, which helps keep valuations low.
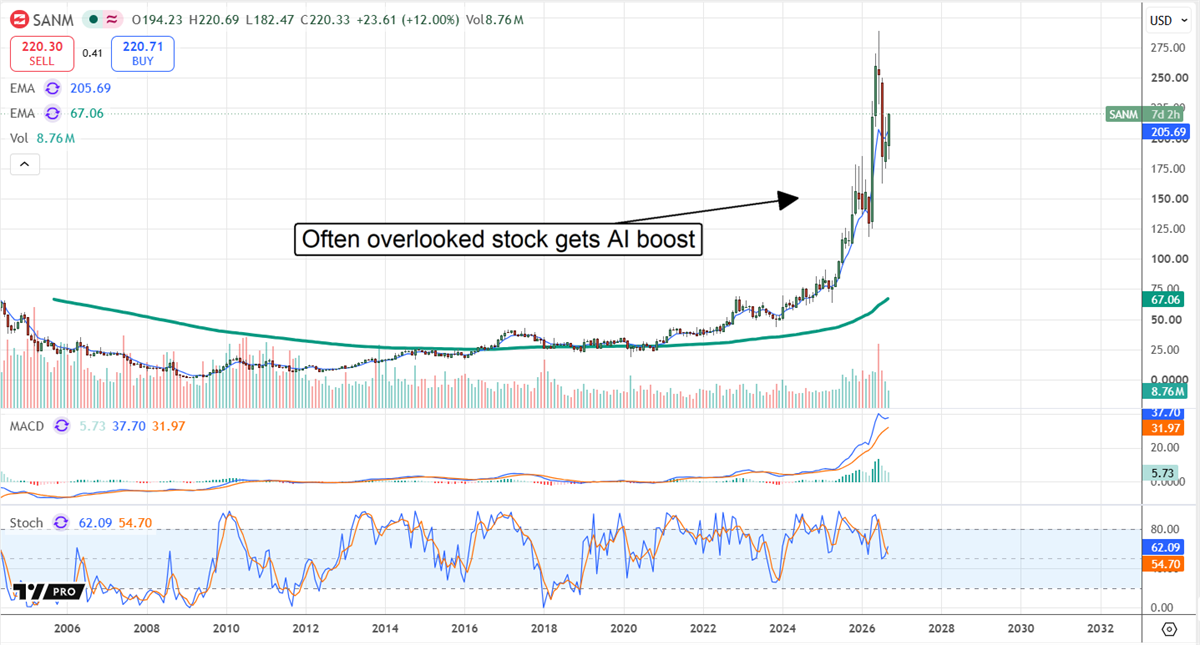
This year, the market is underestimating the impact of AI on this company. Sanmina is leaning into AI by focusing on higher-margin, higher-tech solutions. Catalysts include AMD’s MI450 line and Helios rack-scale systems, of which Sanmina is a preferred manufacturing partner. These programs are expected to drive significant growth over the coming year.
The company doesn’t return significant capital to investors today, choosing to invest in its future, but it may soon, given the business shift. Sanmina is transitioning from a legacy tech provider into an AI-critical name with a deep moat. The moat is built on vertical integration, product penetration, a global footprint, and high switching costs, which create sticky, long-term client relationships. Institutions own more than 90% of this stock and are accumulating aggressively.
SANM’s price action is driven by its latest results. They reflect its position in the AI ecosystem, which the stock has yet to price in. Caution entered the outlook over the summer but did not change it significantly, with analysts' trends pointing to the high-end price target of $260 with higher highs likely. The technical signal is MACD convergence, suggesting existing highs will be retested if not exceeded.
Rickards Predicts: Trump to buy tiny $2 stock? (Ad)
Jim Rickards believes the Trump administration is about to take a direct stake in a $2 stock sitting on the largest mineral reserve in the country - enough gold for a new Fort Knox, enough copper to rebuild the U.S. electric grid 25 times over.
The Trump administration has previously staked positions in MP Materials, Lithium America, Trilogy Metals, and USA Rare Earth - each time shares moved higher. A landmark policy decision expected before November 3 could reprice this stock from $2 to $20 or more within a year.
Click here to see why Rickards believes this stock is next
Delek US Holdings: A Structural Turnaround With Macroeconomic Tailwinds
Delek US Holdings (NYSE: DK) is often overlooked due to its higher-than-average valuations and correspondingly lower yields. However, the narrative is changing in 2026 as margin improvement efforts pay off and structural tailwinds emerge.
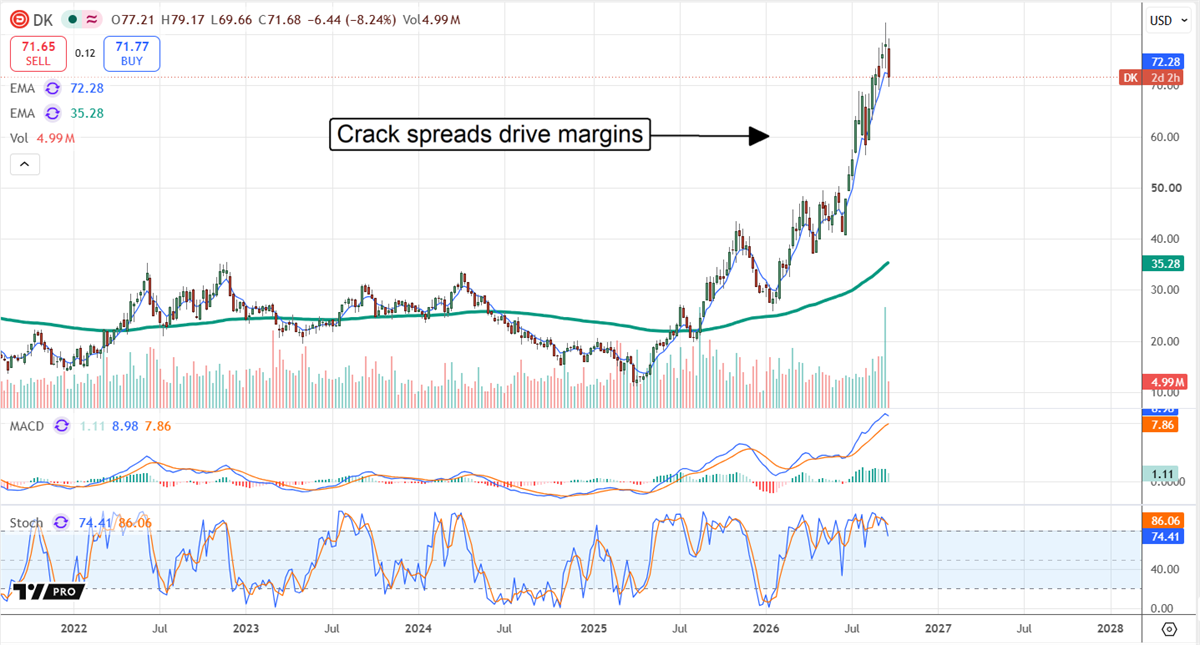
Higher energy prices are affecting cash flow, but crack spreads offset the impact. The crack spread enables wider margins, improved cash flow, and the capacity to execute strategy while paying dividends. Dividends are robust but reliable, yielding in alignment with the S&P 500 average. Institutions own more than 97% of this stock and are accumulating in 2026.
This year’s catalysts include rapidly improving market sentiment. Early 2026 results triggered analyst upgrades and higher price targets, strengthening sentiment and lifting the high end of price targets to $90, 25% upside from late September trading levels.
Looking ahead, analysts are underestimating 2027 results, expecting earnings per share to fall by 50%. They get the impact of lost global refining capacity wrong, and they may also be wrong about the likelihood that crack spreads remain wide through the end of next year. In this scenario, oil prices can implode without significantly hurting refiners, as long as the gap between input and product prices stays wide.
Featured Articles
- 3 Defense Stocks Riding Nuclear, Missile, and Aerospace Demand
- A letter from Shannon Stansberry (From Porter & Company)
- SoFi Is Bypassing the Banking Bottleneck With Stablecoin Settlement
- Analyst nicknamed “The Prophet” issues new warning for America (From Stansberry Research)
- Darden Restaurants Serves Up Fresh Catalysts for a Stock Price Rally
- Best Buy Is Turning Amazon Fire TV Into a New Advertising Opportunity
- MarketBeat Week in Review – 09/21 - 09/25
Stay Ahead of the Market
The best investment opportunities don't wait. Get our research and stock ideas delivered straight to your smartphone—so you never miss a market-moving opportunity. Our text alerts ensure you see timely stock ideas and professional research reports instantly, whether you're in a meeting, commuting, or away from your desk.
