
A free stock pick, from me to you (From Behind the Markets)
Key Points
- Palantir beat third-quarter earnings estimates and raised its full-year revenue guidance.
- Contract bookings growth slowed, raising concerns about whether Palantir can maintain its momentum.
- Palantir shares rebounded from their early Nov. 3 lows, but the stock has yet to establish a clear support level.
- Special Report: Own these 5 stocks before the Nov 3 midterm election (From TradeSmith)
Palantir Technologies (NASDAQ: PLTR) stock fell over 2% in early trading on Tuesday, Nov. 3, following the company's release of its Q3 2026 earnings report after the market closed on Nov. 2. The stock had been down much more in Tuesday's premarket session as investors weighed a slowdown in contract bookings growth despite the earnings beat.
But what may be more interesting is what happened after the market opened on Nov. 3. Specifically, PLTR jumped approximately 4% from its morning low in the first 90 minutes of trading. The rebound suggests buying interest around $165 to $170, although it's too early to call that range a floor for the stock.
That split reaction is the Palantir story in miniature. The fundamentals keep impressing. The perception is that a premium stock can’t afford any hint of deceleration. In the third quarter, investors got a little of both. However, the early price action suggests that some long-term holders may not be ready to hand over their shares just yet.
Today's stock pick is on me (Ad)
Elon can't build his satellite network without one key supplier, and he's paid this company since 2012.
His plan for 1,000,000 satellites could multiply that bill significantly, putting this overlooked stock back in focus.
Dylan has circled December 8th as a key date for this pick.
Claim today's free stock pick before December 8th
Palantir Delivers a Milestone Quarter
Palantir reported third-quarter revenue of $2.31 billion, beating the $2.18 billion analyst estimate. Adjusted earnings of 44 cents per share also topped expectations of 41 cents. The company raised its full-year 2026 revenue forecast to approximately $8.53 billion.
The details were even stronger. U.S. commercial revenue jumped 148% year-over-year to $984 million. For the first time in company history, that topped U.S. government revenue, which grew 96% to $953 million. Total quarterly revenue also crossed $2 billion for the first time.
Profitability kept pace. Adjusted operating margin expanded to 62% from 51% a year ago. GAAP net income reached $1.13 billion. Adjusted free cash flow came in at $1.22 billion, a 53% margin. That pushed Palantir’s Rule of 40 score to 158%.
Guidance was just as bold. Palantir now expects full-year U.S. commercial revenue of at least $3.56 billion, which would be growth of at least 143%. For the fourth quarter, the company guided for revenue between $2.649 billion and $2.653 billion.
Where the Bears Believe They Have a Case
Every quarter, Palantir skeptics voice the same concerns about when the company's growth will normalize. That seemed to gain a little more credibility in the quarter. Total contract value growth slowed to 6% year over year from 49% in the previous quarter. And in the U.S. commercial business, contract value growth cooled to 11% from 153%.
The company signed 64 deals valued at more than $10 million. But that was down from 73 in the prior quarter. Plus, short-term remaining performance obligations (RPO) grew 88% year over year, down from 105% in the prior quarter. The company cited shorter contracts, as customers are testing out open-weight models before committing to longer-term contracts.
Pentagon Eyes 75-Year Rare Earth Deal With This Nasdaq Company (Ad)
The Pentagon is moving to cut US dependence on Chinese rare earth metals, and a Nasdaq-listed company just signed a term sheet for a potential 75-year agreement with the US Army.
The proposed deal would let the company build and operate a rare earth processing facility on an active military base, with the Army getting first right to production. New Pentagon restrictions on Chinese-origin rare earth magnets take effect January 1, 2027.
The company's mine-to-magnet platform covers feedstock agreements, processing, metallization, and downstream manufacturing, with commercial output targeted for 2027.
Read the full breakdown on this rare earth opportunity now
The Story Hasn't Changed for Palantir
The more things change, the more they stay the same. The post-earnings move in PLTR stock was rooted in the idea that a stock and a company are different.
That's been a common criticism of Palantir since the company went public. Investors can love Palantir as a company, but still believe the stock is overvalued.
Those investors will say Palantir isn't different when it comes to valuation. However, in the context of PLTR stock, what does saying it's not different really mean?
Palantir just delivered a level of revenue in one quarter that was nearly equal to its entire revenue in 2023. Analysts are raising their price targets. In fact, the consensus price target of $213.60 is 50% higher than it was 12 months ago.
That's a sign that analysts see Palantir differently than they did one year ago. It also aligns with Palantir chief executive officer Alex Karp's assertion that PLTR is undervalued. The early rebound on Nov. 3 suggests that the stock may be finding its footing, which could interest investors looking for an entry point.
What the PLTR Chart Says About Investor Conviction
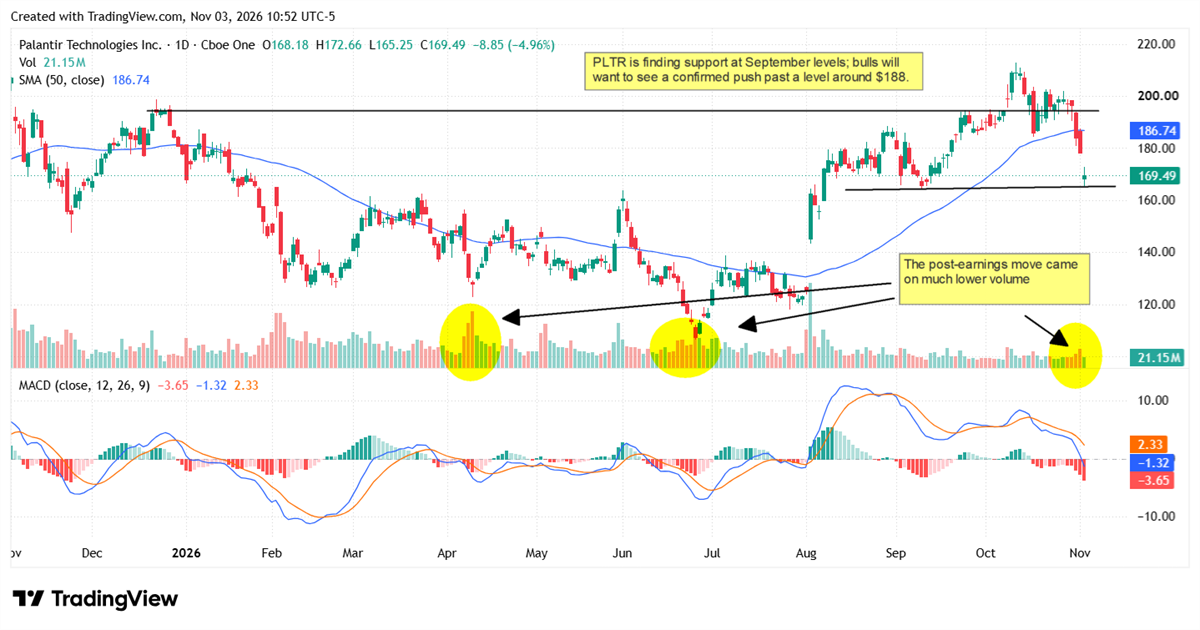
On the surface, the chart doesn’t look encouraging. PLTR gapped below its 50-day simple moving average (SMA), which sits near $173. That line has acted as support since the August breakout. Now it may become resistance.
Momentum also suggests a pullback. The MACD line has crossed below its signal line, and the histogram has turned sharply negative. Technical traders may interpret that as a sign the selling isn't finished.
But look closer, and a different picture emerges. As of early trading on Nov. 3, the stock was down about 20% from its October peak above $210. Sellers have had plenty of reasons to bail. Yet there’s no sign of capitulation. Volume on the gap down is well below the surge that accompanied the August breakout.
Buyers also stepped in near $165. That’s the same area where the stock found support in September before its run to new highs. The rebound suggests some investors still believe Palantir’s long-term growth justifies the premium.
The $165 to $170 range is the level to watch. Holding it would strengthen the case for support. A move back above the 50-day SMA would signal that the bulls have retaken control.
Featured Stories
- Marriott's Earnings Beat Shows Why It's More Than a Bet on Travel Demand
- Elon Musk about to bankrupt Amazon, Microsoft & Google? (From Brownstone Research)
- Franklin Templeton's New ETFs Turn Stock Dividends Into Bitcoin—What's the Catch?
- The chip inside every Tesla (From Behind the Markets)
- Apple's Earnings Beat Comes With a Catch for Investors Heading Into the Holidays
- Republic Services Has the Momentum, But Waste Management Has Another Advantage
- Alphabet's Golden Dome Talks Could Open a New Market, But How Much Is at Stake?
Stay Ahead of the Market
The best investment opportunities don't wait. Get our research and stock ideas delivered straight to your smartphone—so you never miss a market-moving opportunity. Our text alerts ensure you see timely stock ideas and professional research reports instantly, whether you're in a meeting, commuting, or away from your desk.
