
The REAL Reason Trump is Invading Iran (From Banyan Hill Publishing)
Key Points
- Coca-Cola's stock has rallied in 2026 on strong Q3 results, with revenue of $13.4 billion and raised guidance for revenue, earnings, and free cash flow.
- The company's robust cash flow supports its Dividend King status, having raised payouts for more than 60 years at a sustainable 60% of free cash flow.
- Analysts maintain a bullish Moderate Buy consensus with 91.3% buy-side bias among 23 tracked analysts, pointing toward fresh highs near $100 per share.
- Special Report: How to get a stake in Anthropic — before the IPO (From Weiss Ratings)
The Coca-Cola Company (NYSE: KO) stock price has rallied in 2026 and can keep climbing because it's everything AI isn’t: a blue-chip leader that is growing and gaining share, outperforming estimates, and lifting guidance. Most importantly, it is doing so without the costs of AI infrastructure, debt, and free cash flow impairment that come with heavy AI investment.
By contrast, Coca-Cola remains a cash-flow and free cash flow generating machine, sustaining an attractive and growing dividend to underpin its stock price action.
The stock price action is interesting, as it reflects a flight to safety amplified by results that are reinflating the valuation. The stock is a bit expensive, trading at 28x the current-year outlook, but the steep valuation is mitigated by several factors, including outperformance and improving guidance.
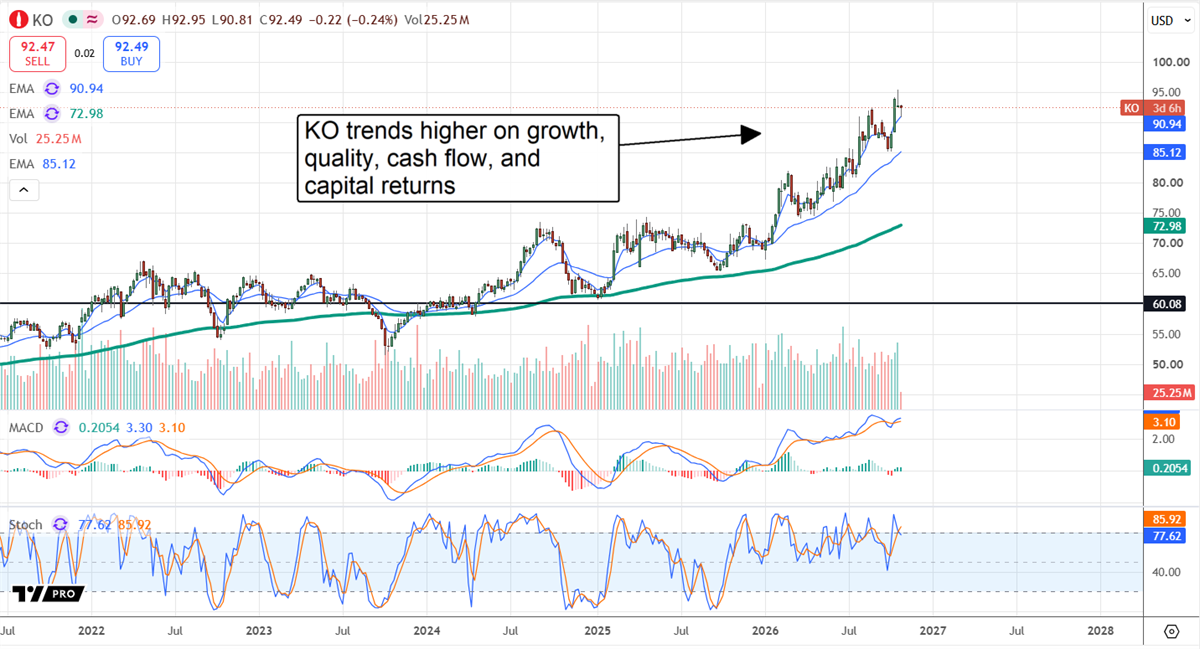
Long-term forecasts also point to a sustained, mid-to-high-single-digit compound annual growth rate over the next 10 years. Based on those forecasts, the stock is valued more favorably at about 16x the 2036 consensus estimate, suggesting 50% stock price upside over time, not including dividends or compounding.
Elon Musk… A Total Fraud? (Ad)
Jeff Brown, the former tech executive who picked Nvidia in 2016 before it surged as high as 37,800 percent, just got inside Elon Musk's new Cybercab, a vehicle with no steering wheel or pedals.
In 2018, the New York Post called Musk a total fraud. Brown's latest footage shows just how far that technology has come since then.
Watch the Cybercab footage and judge Elon Musk's technology yourself
Coca-Cola's Strong Cash Flow Supports Dividend Growth
Coca-Cola's dividend yield is not the highest among consumer staples companies, trailing competitor PepsiCo (NASDAQ: PEP) by half as of late October, but it is still an attractive payout.
The difference between KO and PEP’s payouts comes down to stock price action: KO shares moved higher in 2026 amid market strength.
Coca-Cola's dividend is still double the S&P 500 average and is expected to grow annually. KO is a Dividend King, has increased its payout for more than 60 years, and can sustain increases indefinitely, given its growth trajectory and cash flow. The Q3 payout was 60% of free cash flow, an easily manageable figure that leaves room for share buybacks and balance sheet improvements.
Year-to-date (YTD) balance sheet highlights include steady cash, increased assets, reduced debt, and improved equity. Equity has increased by 15%, reflecting strong cash flow despite dividends, buybacks, and debt reduction.
Buybacks are not substantial, but they keep the share count steady over time and provide investors with a cushion. The company could lean more heavily into buybacks over time to reduce its share count and sustain strong earnings per share growth, even when business conditions are less favorable.
Coca-Cola's Strong Q3 Results Drive Higher Guidance
The Coca-Cola Company had a solid Q3, growing by 7.4% to $13.4 billion in net revenue, nearly half a billion better than the consensus forecast. Strength was underpinned by 7% organic growth, in turn supported by a 7% increase in concentrate sales and a 1% favorable impact from price and mix. As usual, unit case volume did not track concentrate due to timing, but it was also solid, growing 5%.
By operating segment, Latin America led, aligning with reports from other consumer-oriented brands such as Whirlpool (NYSE: WHR), growing by 16%, followed by a 12% increase in Bottling Investments. Europe, Middle East & Africa (EMEA), North America, and Asia Pacific markets each grew by single digits.
By beverage category, sparkling soft drinks, which include Trademark Coca-Cola, grew by 5%. Water, sports, coffee and tea also grew 5%, while juice, value-added dairy and plant-based beverages were flat.
Margin news was good. The company logged margin improvements on a GAAP and adjusted basis, with adjusted operating margin up by 100 basis points (bps). Adjusted earnings grew an accelerated 11%, beating estimates by 3 cents, or 340 bps, and these results led management to raise guidance.
Guidance is a catalyst for this market. Management raised guidance for revenue, organic revenue, adjusted earnings, and free cash flow, placing them all above consensus forecasts. The likely outcome is that the company performs at the high end of expectations, potentially outperforming guidance, and provides a favorable outlook for next year. Catalysts include portfolio optimization, a focus on high-growth categories such as low-calorie/no-sugar, and a new partnership with KFC. Ironically, KO also benefits from AI, using it to help optimize operations and consumer engagement.
Army Picks One Firm for Heavy Rare Earth Processing (Ad)
China controls more than 90% of global rare earth alloy production, leverage it is using to restrict exports to the U.S.
With a January 1, 2027 deadline approaching, the Pentagon selected four companies to build critical mineral processing facilities on U.S. military bases. Only one was chosen for heavy rare earths - a Nasdaq-listed firm with an Ohio metallurgy facility under Pentagon contracts and rights to 80% of output from a major Canadian processing plant.
See why this rare earth stock deserves a closer look today
Analysts Point to Fresh Highs for KO Stock
Bullish analyst trends are strengthening after Coca-Cola's Q3 release. Trends include increased coverage, firming sentiment, and a 91.3% Buy-side bias to the Moderate Buy rating. Investors can assume moderately high conviction in the rating, given that 23 analysts are tracked and the price target trend forecasts modest upside to the consensus and about 13% to the high end.
Analyst trends remain bullish, and the consensus price target is sufficient for a fresh high, which matters given the technical signal. A move to fresh highs will likely hit $100 before peaking.
Read More
- Apple's Foldable iPhone Sold Out in Minutes, But Wall Street Has Questions
- Big Gains on Tap as Sub-US$1 Silver-Gold Discovery Takes Shape (From Resource Stock Digest)
- Netflix Is Making Big Changes, But Can It Fix What's Really Hurting Growth?
- How options let you do more with less capital (From Base Camp Trading)
- Charging Ahead: Solid Power’s Pilot Line Leaves the Lab
- Off-Price, High-Yield: Why Ross Stores Is Defying the Retail Slump
- Whirlpool's Stock Collapse Raises a Bigger Question About Its Recovery Potential
Stay Ahead of the Market
The best investment opportunities don't wait. Get our research and stock ideas delivered straight to your smartphone—so you never miss a market-moving opportunity. Our text alerts ensure you see timely stock ideas and professional research reports instantly, whether you're in a meeting, commuting, or away from your desk.
