
Analyst nicknamed “The Prophet” issues new warning for America (From Stansberry Research)
Key Points
- SpaceX's plan to end shared Falcon 9 missions after 2028, driven by Starlink's heavy capacity use, is tightening orbital launch supply and raising prices.
- Independent launchers like Rocket Lab and Firefly Aerospace are capturing displaced demand through growing backlogs, new facilities, and premium-priced launch contracts.
- Satellite operators such as Planet Labs face rising launch costs and margin pressure, though cash reserves may help them withstand higher capital expenditures.
- Special Report: [Free Report] The 11-Hour Options Guide for Beginners - trade and ticker included (From Base Camp Trading)
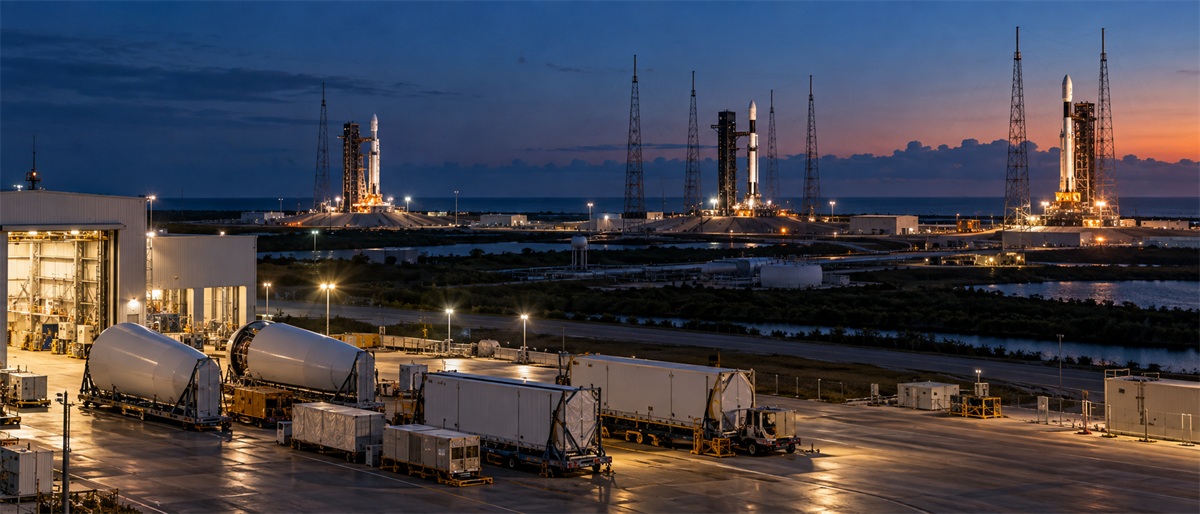
For years, the commercial space economy operated on a predictable assumption: getting hardware to orbit was getting cheaper. That calculus changed abruptly when SpaceX (NASDAQ: SPCX) indicated it will stop selling shared Falcon 9 missions beyond 2028. With its Starlink internet constellation now consuming approximately 79% of Falcon 9 capacity, SpaceX is prioritizing internal deployment over third-party logistics.
While the surface read is standard corporate consolidation, the underlying reality points to a supply shock. Orbital launch capacity is transforming from a widely available commodity into a heavily constrained asset. This structural shift creates a clear divide for investors analyzing the sector. Launch providers now hold substantial pricing power, while satellite operators who rely on buying those rides face escalating capital expenditures. The current launch landscape shows a closing window of opportunity for independent hardware builders and growing financial risk for businesses caught on the wrong side of the payload fairing.
She knows the real him - and why he almost walked away (Ad)
Porter Stansberry nearly canceled the entire project. When he first saw the claimed returns - only one down year in nearly two decades and total gains of almost 2,000% - his immediate reaction was disbelief.
It took a trusted friend's personal vouching for Emmet Savage and a face-to-face trip to Ireland to change his mind. The full documentary, Investigating Project Prophet, is now live.
Watch the full story and see the verified track record for yourself
Payload Pain: Tracking the 2028 Falcon Squeeze
SpaceX recently raised its standard rideshare rates to around $7,000 per kilogram. This provides immediate, empirical evidence that the capacity squeeze is actively inflating costs well ahead of the 2028 shared-mission cutoff. SpaceX has a market capitalization of about $1.93 trillion and generates about $18.67 billion in annual sales. A recent Nasdaq-100 rebalancing doubles the index weighting for SpaceX, forcing index funds to buy billions in shares and highlighting institutional confidence in this pricing dominance.
When a single provider controls most commercial lift, a policy change ripples across the entire supply chain. The sudden evaporation of third-party rideshare availability forces satellite operators to seek alternative transport, creating an overflow of demand for a limited number of operational rockets.
In the aerospace sector, demand does not neatly wait for supply to catch up. Satellites in low Earth orbit experience atmospheric drag and radiation degradation, requiring constant replenishment to maintain coverage. For companies that sell data from space, pausing launches is rarely an option. This dynamic forces operators to accept higher launch prices, shifting the economic leverage directly into the hands of the few companies capable of reaching orbit.
Ignition Sequence: Launchers Grabbing Market Share
Independent launchers are moving quickly to monetize this bottleneck. Rocket Lab USA (NASDAQ: RKLB) stands out as a primary beneficiary, with a record backlog approaching $2.36 billion.
Rocket Lab currently commands a market capitalization of around $42.5 billion, supported by second-quarter revenue of $234.1 million, up 62% year over year.
As SpaceX steps back from the shared market, Rocket Lab is securing early manifests for its upcoming medium-lift Neutron rocket at $50 million to $55 million per launch, without needing to offer significant discounts to attract payload operators.
Execution remains the gating factor. Management targets pad delivery for the Neutron rocket around the fourth quarter of 2026, meaning actual commercial launches will likely bleed into 2027. Rocket Lab is insulated by predictable government revenue while it scales, anchored by a recent $266 million U.S. Space Force contract extending through 2028.
Firefly Aerospace (NASDAQ: FLY) is similarly scaling its physical infrastructure to capture orphaned payloads. Firefly Aerospace recently inaugurated a new cleanroom in Cedar Park, Texas. This expansion effectively quadruples its manufacturing footprint, enabling simultaneous assembly of up to 12 lunar landers and orbital vehicles.
The fundamentals show physical readiness, even as Firefly Aerospace trades around $22, a deep discount from the August 2025 initial public offering price of $41 to $43. Recent quarterly revenue surged about 659% year over year, and Firefly Aerospace posted an earnings-per-share beat of negative 42 cents versus a negative 50-cent consensus.
Backed by institutional investors like BlackRock, which holds a 3.68% stake, Firefly Aerospace is positioning itself to convert the industry's capacity squeeze into tangible revenue visibility.
WATCH THIS BEFORE SEPTEMBER 25TH!! (Ad)
James Altucher says a quiet government filing could reveal Elon Musk's biggest move yet, and almost nobody has noticed it.
Altucher believes the filing could matter to as many as 1,806,000 Americans in the years ahead. He explains why Musk buried it and what it could mean, free of charge.
Watch the free breakdown before September 25th to learn more
Burning Up on Reentry: Operator Margins Under Pressure
The buy-side of the launch market paints a different financial picture. Satellite operators require continuous orbital access to maintain and upgrade their constellations. As rideshare options evaporate and dedicated launch prices rise, these operators face direct threats to their unit economics.
Planet Labs PBC (NYSE: PL) exemplifies this vulnerability. Planet Labs topped recent quarterly estimates with a 58.2% jump in year-over-year revenue, reporting earnings per share of 2 cents. However, Planet Labs operates with deep net margin deficits hovering around -95.13%, recording a recent net income of negative $246.86 million. Expanding its constellation to serve commercial and government clients requires frequent, reliable launches. Higher transport costs translate directly into higher capital expenditures, delaying Planet Labs' path to profitability.
Planet Labs holds a critical defensive moat in the form of liquidity. Recent filings show Planet Labs maintaining around $865 million in cash and short-term investments. This provides a substantial operational runway to absorb higher transport costs without needing immediate dilutive financing.
Caution remains evident among insiders, as highlighted by executive Robert Schingler's sale of over 52,000 shares in mid-September 2026, alongside bearish short interest. Investors evaluating satellite operators should weigh this margin compression against their available cash buffers to determine if they can weather the pricing storm.
The Starship Shadow: Clocking the Supply Shock Window
The core question for this trade is how long the pricing power lasts for independent launchers. The 2028 shared-mission cutoff creates a defined window of scarcity, but SpaceX is concurrently developing its next-generation Starship vehicle. Once Starship is commercially ready, it threatens to re-flood the market with low-cost lift capacity, effectively erasing the bottleneck.
Until Starship achieves a regular commercial cadence, the supply constraint is real. Legacy launchers have a few years to secure long-term agreements at premium rates, while satellite operators must navigate higher costs and manage their balance sheets carefully.
Investors may want to monitor the execution timelines for vehicles like Rocket Lab USA's Neutron and Firefly Aerospace's Alpha rocket, as production delays could limit their ability to fully capitalize on the current supply shock. Those evaluating the space sector might consider how each launcher balances immediate constraints with the eventual introduction of heavier-lift alternatives.
Featured Articles
- Cintas Raises Guidance as a Major Catalyst Moves Closer
- A Wall Street Veteran's Weekly Options Strategy Explained (From Base Camp Trading)
- Dave’s Success Has Investors Split
- The trading strategy that works BECAUSE you have a life (From Tim Sykes)
- Hims & Hers Slides Nearly 7% as Legal Pressure Adds to Its Growing List of Risks
- Paychex Plunges, Providing the Entry Investors Have Been Waiting For
- The Case for Buying High-Yield General Mills Just Strengthened
Stay Ahead of the Market
The best investment opportunities don't wait. Get our research and stock ideas delivered straight to your smartphone—so you never miss a market-moving opportunity. Our text alerts ensure you see timely stock ideas and professional research reports instantly, whether you're in a meeting, commuting, or away from your desk.
